The IMF projects Venezuela’s GDP to grow 5% in 2026, while monthly inflation slowed in September. However, the minimum wage has remained frozen since 2022. Economist Carlos Dürich attributes this gap to oil’s dominance, the weakness of other sectors, and the unequal distribution of foreign currency.
By Neirlay Andrade
Venezuela is once again reporting economic growth figures that contrast sharply with the difficulties many households face in meeting their basic needs. International Monetary Fund (IMF) projections point to a 5% expansion in gross domestic product (GDP) in 2026, while the Central Bank of Venezuela (BCV) reported that monthly inflation fell from 13.8% in August to 8.4% in September.
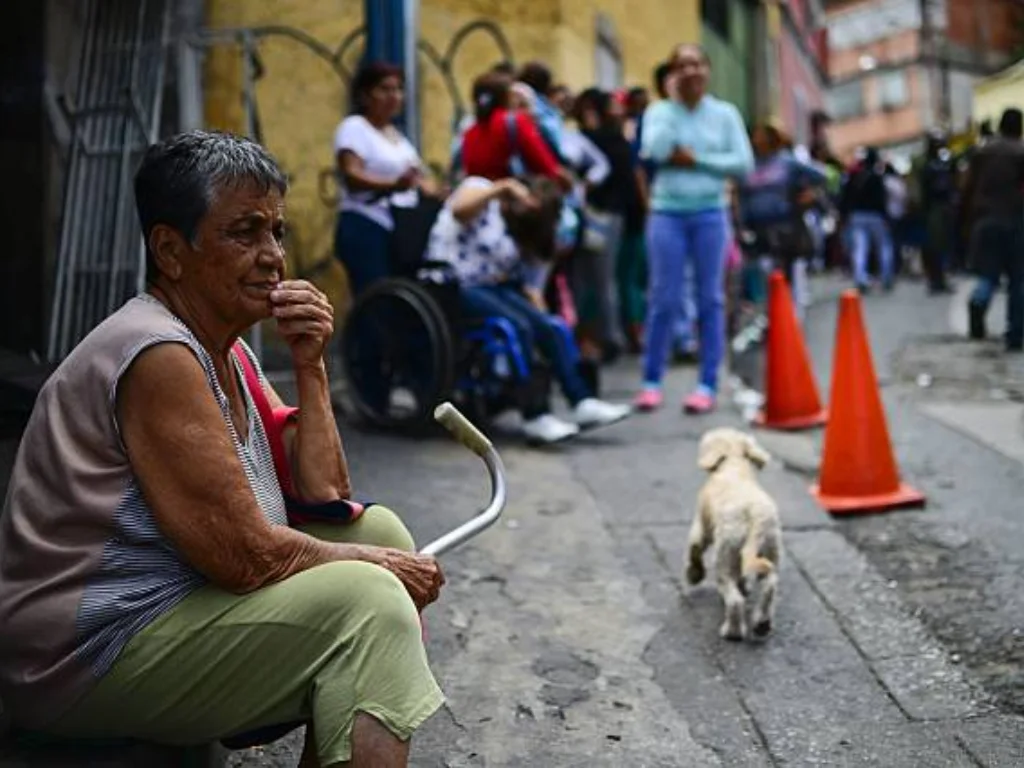
However, this does not mean that products have become cheaper or that household incomes have regained their purchasing power. The legal minimum wage has remained frozen at 130 bolivars per month since March 2022—approximately 10 U.S. cents—and, as a result, benefits such as vacation pay, Christmas bonuses, and severance payments have lost much of their value.
In August, a family of five needed $755.36 to cover its basic food basket, according to the Center for Documentation and Social Analysis of the Venezuelan Teachers’ Federation (Cendas-FVM).
The gap between macroeconomic indicators and the population’s material living conditions raises a question: Why does an economy that is growing again not necessarily translate into widespread improvements in well-being?
For economist and university professor Carlos Dürich, the answer lies beyond the figures: it requires examining which activities drive expansion, how benefits are distributed, and what happens to sectors that do not participate in that growth.
Growth driven by oil
In October, the IMF raised its forecasts for Venezuela. In its World Economic Outlook (WEO), published on October 13, the organization projected GDP growth of 5% for 2026, up from the 4% forecast in April, and 7% for 2027, compared with its previous estimate of 6%. At the same time, it estimated that average annual inflation would reach 467.9% this year before moderating to 174% in 2027.
The organization’s forecasts reflect an economy that can expand production while still experiencing severe price imbalances. For Dürich, one key factor is the sectoral composition of growth.
“Because economic growth is driven by a single sector, the oil sector, […] there is not as much job creation or development of downstream economic activities,” he explains.
Oil operations require substantial investment in infrastructure, equipment, and technology, but they do not necessarily generate employment in proportion to increases in production or revenue.
“The rest of the economy, the other non-oil sectors, tend either to contract […] or to experience slower growth,” the economist maintains.
This interpretation highlights the distinction between economic growth and a broad-based economic recovery: GDP can increase because of certain activities without all productive sectors benefiting equally.
Acting President Delcy Rodríguez stated on October 8, during the 82nd Annual Assembly of Fedecámaras, that Venezuela’s economy had recorded 22 consecutive quarters of growth. She also reported that domestic consumption had increased by 21.3% so far this year.
These figures support the government’s argument that the economy is recovering. However, an increase in aggregate consumption does not, by itself, reveal how much household purchasing power has improved.
Importing more does not mean producing more
Dürich also identifies the relationship between rising oil revenues, imports, and the competitiveness of domestic production.
The economist explained that the influx of imported agricultural products can put pressure on Venezuelan producers, particularly when they must compete with goods from economies that benefit from larger production scales, financing, and government support.
As an example, he cited the difficulties domestic corn and rice producers face when competing with imports of those crops and soybeans from the United States.
“Those products from the United States come from a favorable economic environment, with federal government subsidies and lower tariffs to encourage exports. As a result, they arrive at our ports at much lower prices. Domestic producers have two options: either match the prices their competitors offer or drastically reduce their ability to compete,” the professor explains.
According to his analysis, when local producers cannot compete with the prices of imported goods, they may have no choice but “to sell less, produce less, invest less, and cultivate fewer productive hectares.”
Dürich also believes that the mechanisms through which foreign currency enters and circulates within the economy influence this process. In his view, when oil revenues flow into the private sector without sufficient distribution to finance domestic production, they can drive higher imports.
“When you encourage more imports, you make domestic industry less competitive,” he warns.
Access to foreign currency: A key part of the problem
The distribution of foreign currency is another central element in the economist’s explanation. Although the U.S. dollar serves as a benchmark for setting many prices, not everyone has equal access to foreign currency or can purchase it at the same exchange rate.
Dürich argues that the gap between the official exchange rate and the parallel market rate stems partly from unequal access to foreign currency. Economic actors who cannot obtain dollars through official mechanisms must turn to alternative channels.
The economist claims that, out of approximately $10 billion to $11 billion in foreign currency allocated during the year, less than 10% went to retail foreign exchange transactions.
“We have a large segment of the population that cannot access those dollars provided by the Central Bank of Venezuela at the Central Bank’s exchange rate and must turn to the open market,” he explains.
According to his analysis, the consequence is that small business owners and other economic actors who need foreign currency to replenish inventories may face exchange costs higher than those established by the official rate.
“The fetishism of quantification”
“During this oil boom, as with any period of economic growth, we must look not only at indicators—such as gross domestic product growth or declining inflation—but also at how these two indicators interact with the rest of the economic processes,” the university professor explains.
Dürich clarifies that in an economy “where ownership and capital are concentrated,” GDP growth “simply shows that the wealthiest sectors generate more wealth and concentrate even more of it.”
The same applies to inflation, he says. “Inflation is always viewed as an indicator that benefits the vast majority when it decreases and harms them when it increases. That is true up to a point, because a certain level of inflation is characteristic of a growing economy, an expanding economy.”
At the heart of Dürich’s reflections lies the work of Argentine mathematician Oscar Varsavsky, who discussed “the fetishism of quantification,” a phenomenon that involves “placing unquestioning faith in numbers rather than in qualitative evidence, in how people actually feel.”
“We need to understand all these dynamics rather than focusing solely on two indicators [GDP and inflation] that, on their own, do not necessarily tell us very much,” he concludes.